Insurance exhibit
We identify the parties and activities the contract asks you to insure.
Commercial insurance / San Francisco
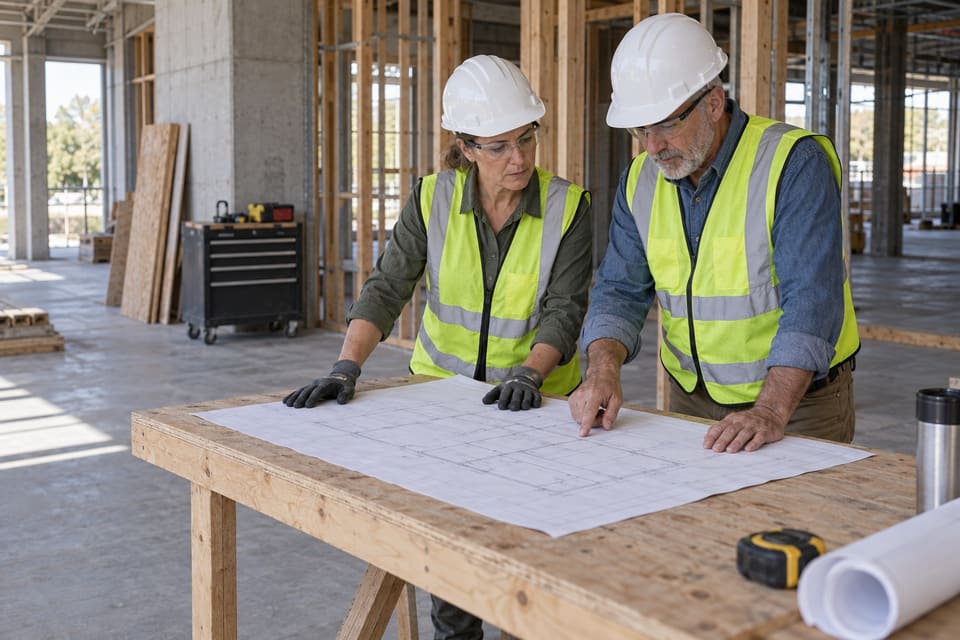
We arrange insurance for general contractors and specialty trades. We prepare your submission, shop the market, and read the proposals against your scope of work and contract requirements.
Contractors we work with
We distinguish the risks you supervise as a general contractor from the work you perform as a trade, and put those details into the submission.
Before mobilization
We compare the insurance requirements written into the construction contract with the coverage actually proposed for the work.
Owners and general contractors ask for limits, additional-insured status, and completed-operations wording. We check each requirement against the proposal before you sign the subcontract.
Who you hire changes both the liability picture and the premium at audit. We record the trades you subcontract and the certificates you collect from them.
Work in progress and completed work are treated differently, and a project can outlast the policy. We check how each proposal responds once the crew has left the site.
Construction coverage
We compare the policies covering your liability and workforce with the project property insurance assigned by the construction contract.
Choose a policy to read about
General liability can cover third-party injury and property damage arising from your work. We compare the construction exclusions and endorsements with the projects you take on.
What we check in the quotes
Builders risk can insure physical damage to a construction project and its materials. We check who must arrange it and seek terms for the property assigned to your responsibility.
What we check in the quotes
Workers compensation addresses employee work-related injuries. We help describe your crew’s duties and payroll accurately, request terms, and review the employers liability portion of the proposal.
What we check in the quotes
Our policy review
The certificate records insurance information; the policy determines coverage. We read the forms behind it and explain whether the wording addresses the owner or general contractor’s insurance request.
We identify the parties and activities the contract asks you to insure.
We check the proposed endorsements for the requested protection.
We flag restrictions affecting the construction work you perform.
Tell us about the next project or renewal. We will help establish the requirements and get the insurance submission underway.
From submission to recommendation
You explain the work. We prepare the account for the market and take the proposals through a detailed comparison.
We establish the work you perform and subcontract, then assemble the project and payroll details needed to request terms.
We approach the market with your account and handle the follow-up on construction activities and contract requirements.
We compare premiums with the forms and endorsements, explaining which option we recommend and which conditions still need attention.
When the project changes
Before you ask for a certificate
See how certificates, additional-insured endorsements, and project property cover apply to common contractor requirements.
A certificate reports insurance information; it does not amend the policy. If an owner requests additional-insured protection or other wording, we compare that request with the actual policy endorsements. Naming a certificate holder does not by itself provide additional-insured status.
An allegation can involve work that has already been handed over. A contract may request additional-insured protection for both ongoing work and completed operations, but the endorsement addressing one does not necessarily address the other. We check the scope and duration of both provisions when comparing contractor liability quotes.
The construction agreement is the starting point for identifying who has that responsibility. Then confirm whose interests and which property the actual policy includes. We examine an owner-arranged policy for contractor obligations, deductibles, and property outside its scope.
Fort Mason
Contractors in San Francisco can finish an installation and move to another job while the first subcontract still requires completed-operations cover. We include those obligations when shopping your liability insurance. We check the proposed endorsements for both the work underway and the work already handed over, so your renewal accounts for more than the next certificate request.