Commercial coverage / contractors
Insurance for your construction operations and projects.
We shop the contractor account with the project requirements in hand. The comparison covers the relevant forms and exclusions, with an explanation of the terms we recommend.
Commercial General Liability
General liability can cover third-party injury and property damage arising from your work. We compare the construction exclusions and endorsements with the projects you take on.
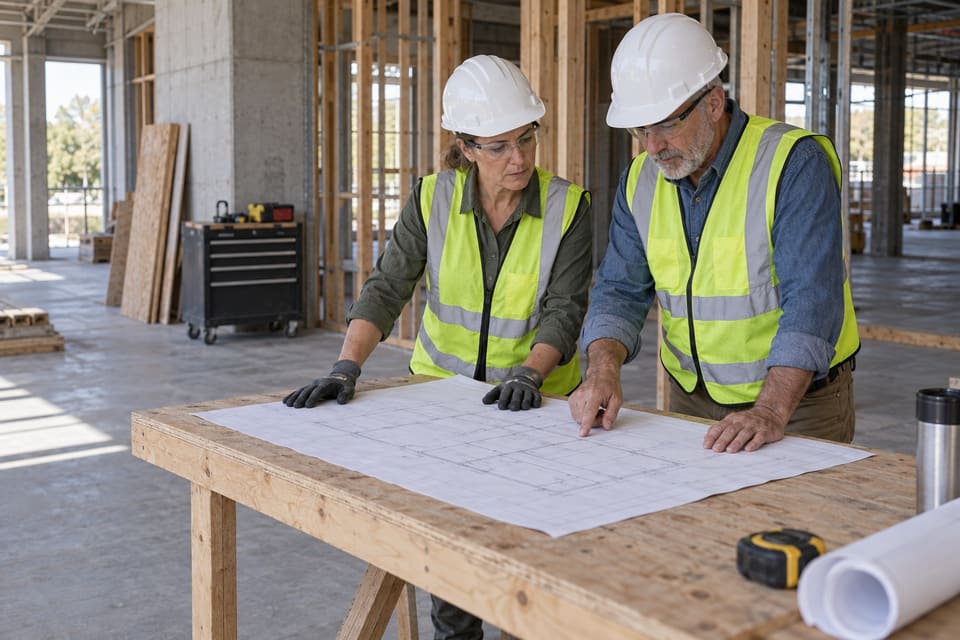
Liability insurance for construction work
We examine cover for work in progress and completed operations separately. Our review flags restrictions on construction type or subcontracting and checks additional-insured wording against the obligations you have accepted.
For renovations beside occupied space, we examine liability cover for damage to neighboring property or injury to people using the building. We also explain restrictions on correcting your own defective work.
What we check in the proposal
- We reconcile the contracting entity with the named insured.
- We read additional-insured protection for both ongoing and completed work.
- We check whether the proposal includes a requested per-project aggregate.
- We flag residential, height, or excavation restrictions that affect your scope.
Builders Risk
Builders risk can insure physical damage to a construction project and its materials. We check who must arrange it and seek terms for the property assigned to your responsibility.
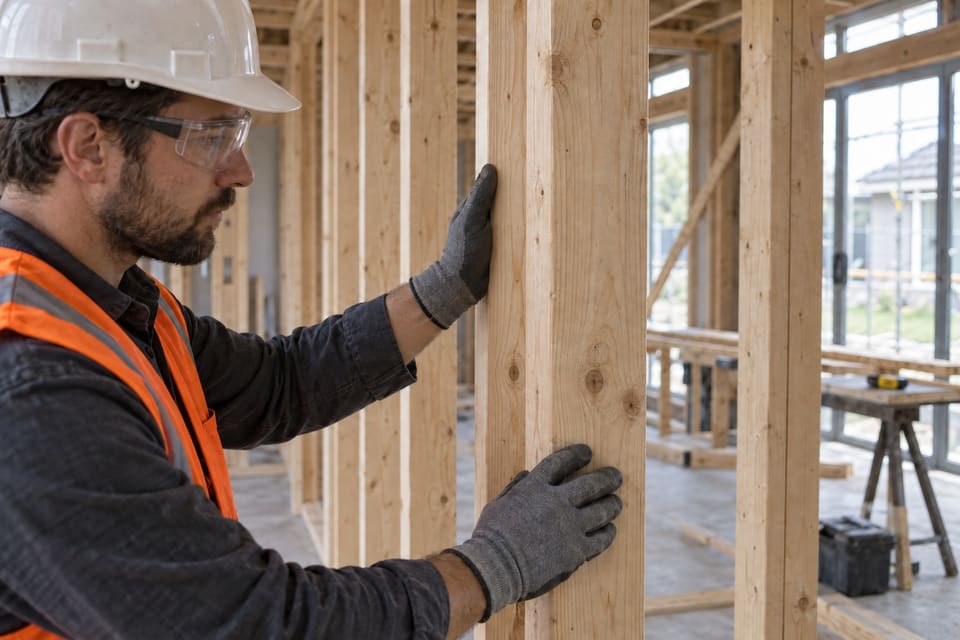
Insurance for the project under construction
We read the property insurance clause in the construction agreement, then compare the proposed policy with the project value and dates. Existing structures and the interests of the owner and contractor need explicit attention.
A renovation can include stored finish materials and an occupied existing building. We describe those interests separately in the submission and show you how each appears in the proposed cover.
What we check in the proposal
- We identify cover for existing structures as well as new work.
- We examine off-site storage and transit terms for project materials.
- We explain theft and water-damage conditions, including flood and earthquake treatment.
- We check when cover ends and how occupancy or delays affect that date.
Workers Compensation and Employers Liability
Workers compensation addresses employee work-related injuries. We help describe your crew’s duties and payroll accurately, request terms, and review the employers liability portion of the proposal.
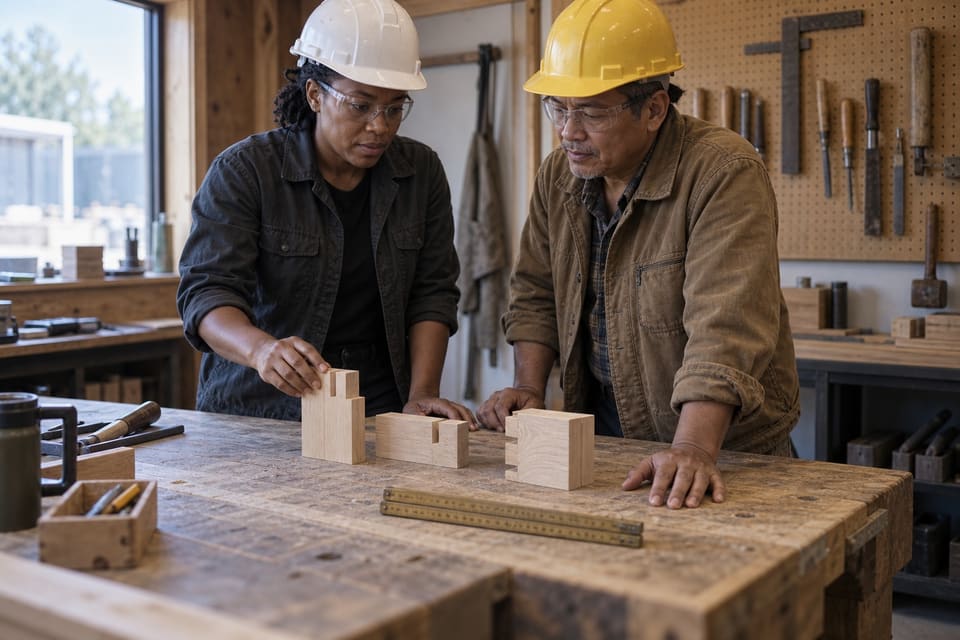
Workers compensation for your construction crew
We work through field duties, supervision, and office roles when preparing the payroll submission. If your business adds a new trade activity or expands its crew, we help identify the information needed for the insurance account.
If your crew takes on a new installation activity, we help update the description used to seek insurance. That gives the market the current work rather than an application carried forward from an earlier scope.
What we check in the proposal
- We describe the duties behind each construction activity.
- We work with you to update payroll estimates for the current workload.
- We identify supplied-labor and subcontractor arrangements in the submission.
- We check contract requests for waivers of subrogation.
We identify other cover the work may need.
Construction vehicles and tools can need cover beyond these policies. We also identify design or pollution responsibilities and higher liability requirements, so the submission reflects the full scope you describe.